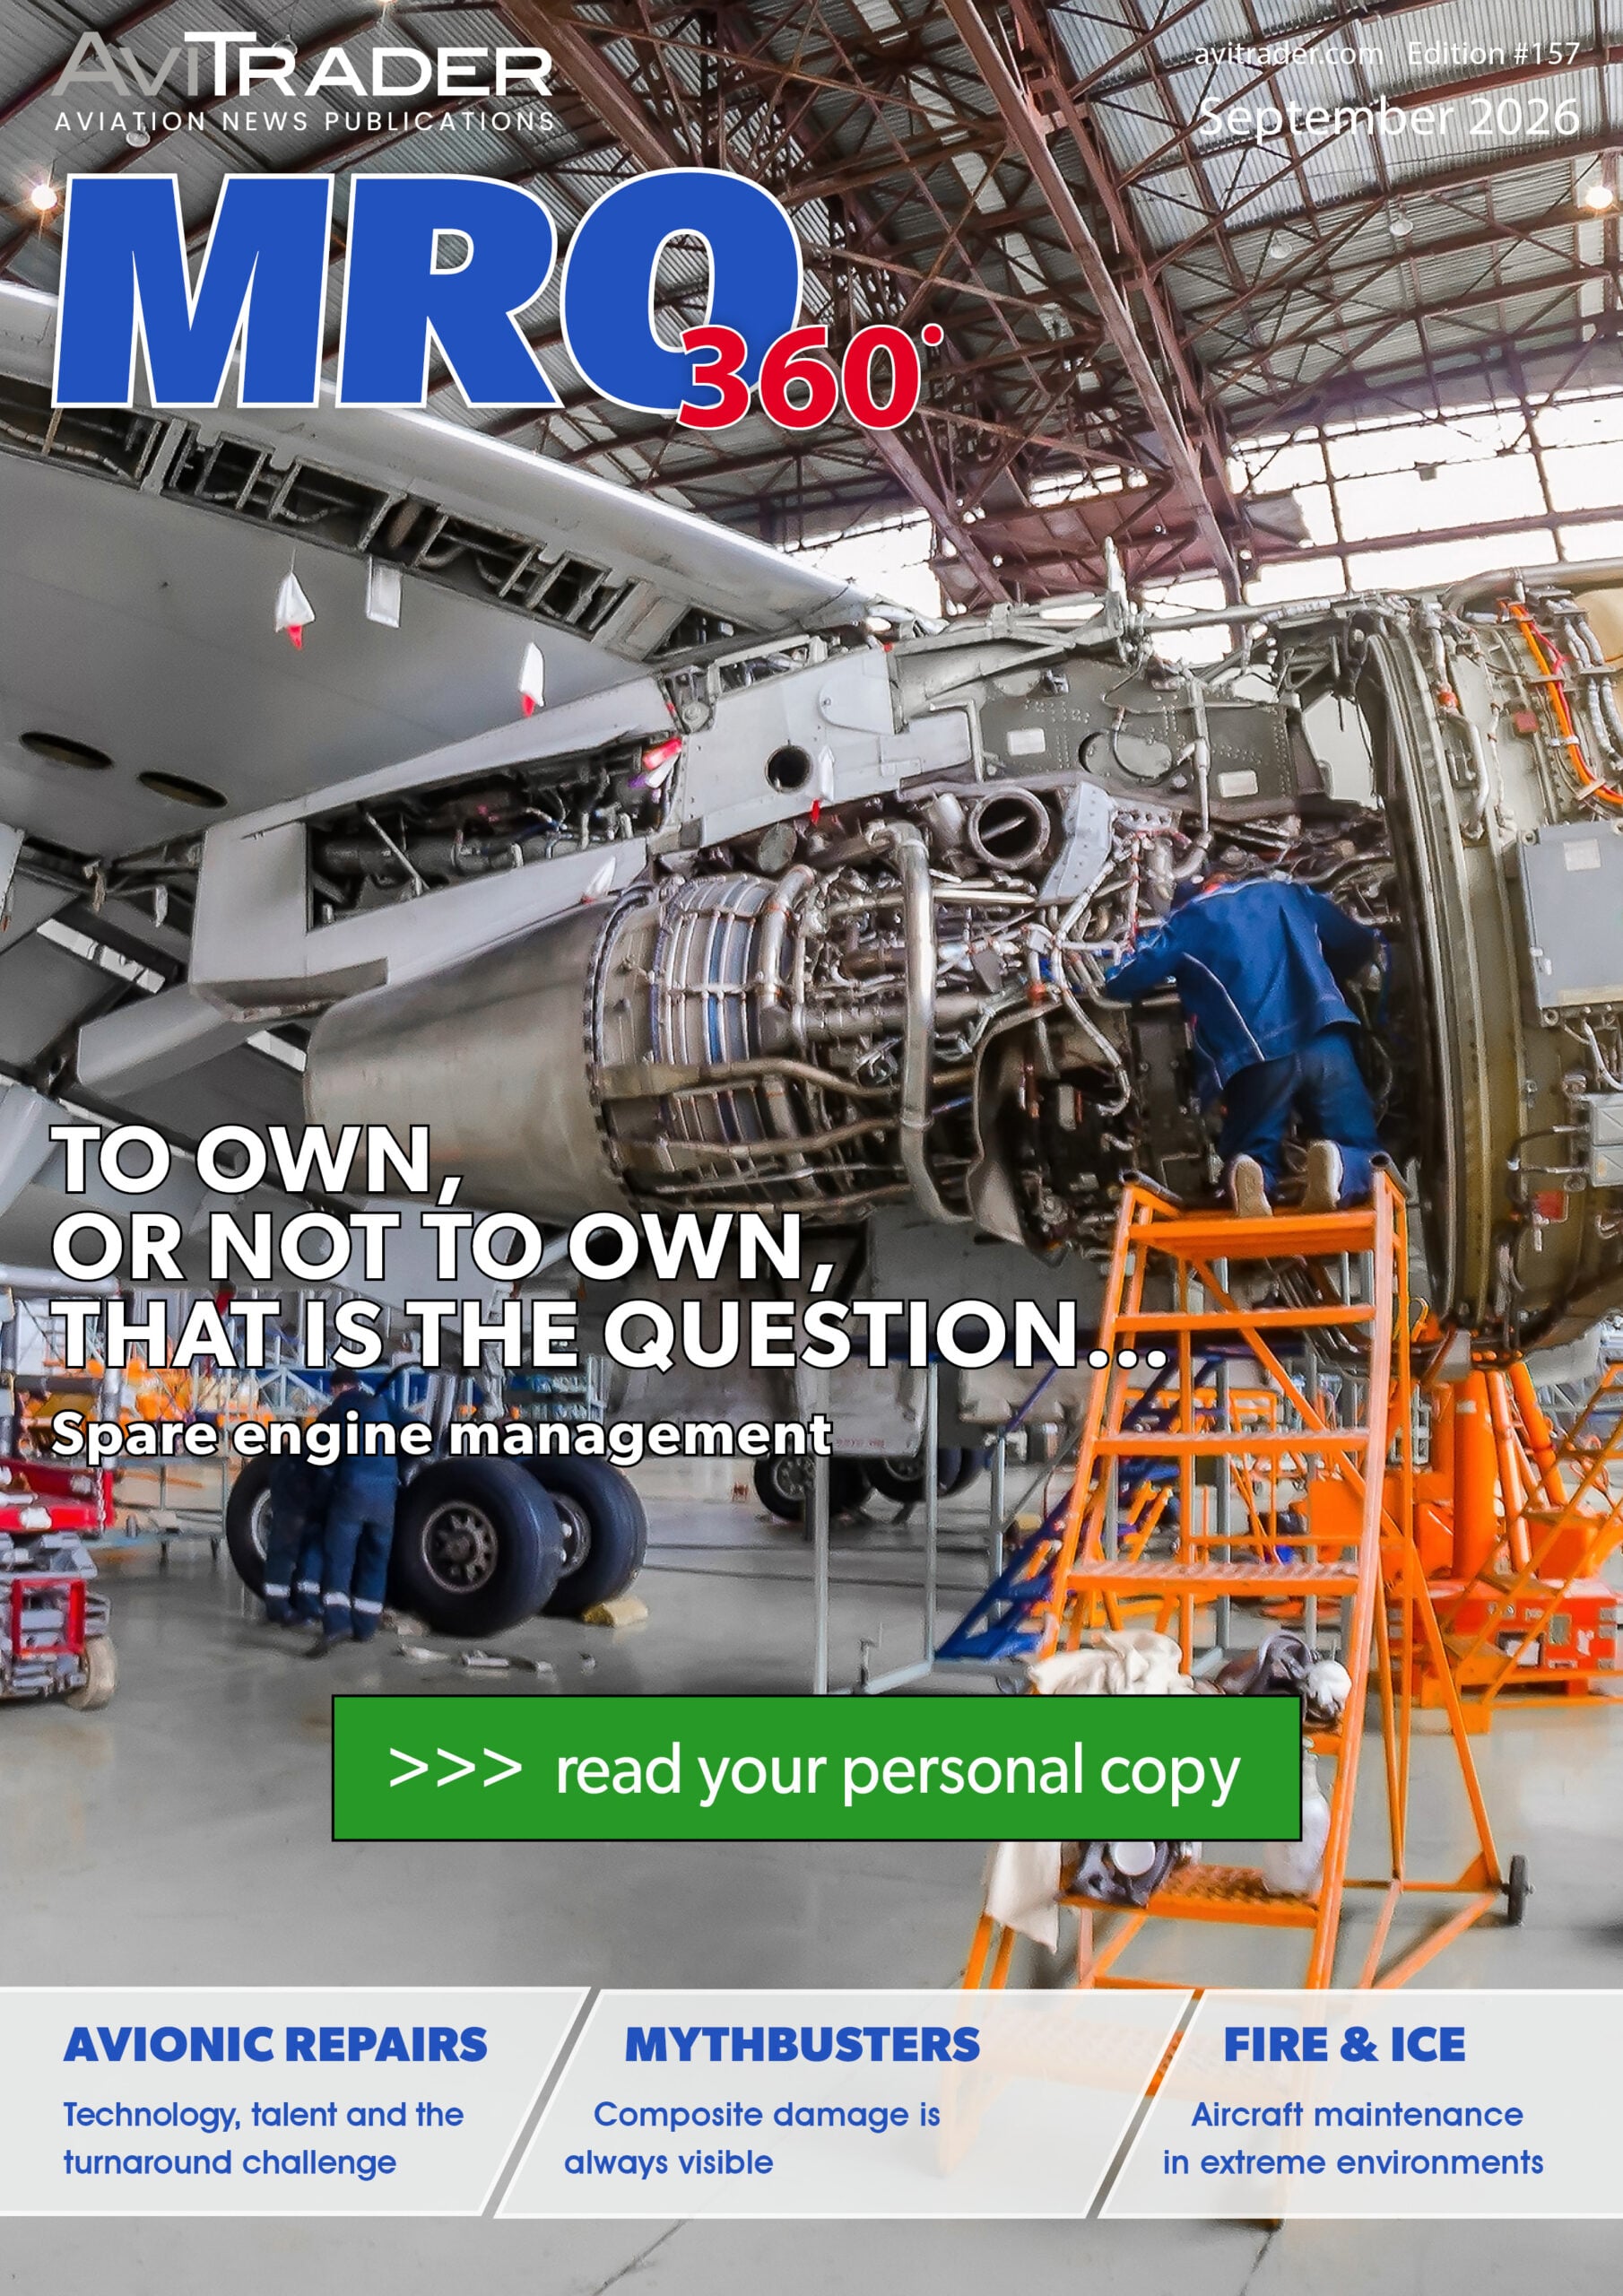
To own, or not to own, that is the question…
For airlines, spare engine management has always involved balancing cost against operational security. In today’s ultra-challenging operating environment, however, achieving that balance has become considerably more difficult. Extended engine shop visit turnaround times, constrained MRO capacity, supply chain disruption and pressure on engine availability mean that achieving the right spare engine coverage can be critical to maintaining fleet reliability and avoiding costly aircraft downtime. At the same time, the substantial capital tied up in spare engines has upped the temperature on the debate as to whether outright ownership remains the most effective solution. Leasing, pooling and other flexible access models can offer attractive alternatives, while the differing support requirements of mature and new-generation engine programmes add another layer of complexity to long-term planning. Consequently, there is no simple formula for determining how many spare engines an airline needs, how they should be sourced, or when they should be available. Cost, fleet size and utilisation, maintenance schedules, engine reliability, shop capacity and acceptable levels of operational risk all have a part to play. We asked ten industry specialists to share their perspectives on these challenges so we could get a better feel for what ideal spare engine solutions look like today.
What are the biggest challenges airlines currently face in managing their spare engine requirements?
Spare engine planning is no longer simply a matter of maintaining a predetermined spare ratio. Airlines are now operating in an environment characterised by extended and often unpredictable shop turnaround times, engine durability concerns, material shortages, constrained MRO capacity and rising costs for serviceable engines. Demetrios Bradshaw, Chief Executive Officer at Aeras Aviation explains further: “From a technical perspective, an available engine is not necessarily a usable engine. The correct model, build standard, thrust rating, LLP status, configuration, QEC requirements and remaining life must all align with the operator’s fleet and mission profile. Equally important are complete records, traceability and regulatory compliance. The commercial challenge is balancing operational resilience with capital efficiency. Excess spare capacity can tie up significant capital, while insufficient coverage can result in aircraft groundings, schedule disruptions and lost revenue. At Aeras, we view spare engine planning as a dynamic process that combines removal forecasts, shop turnaround times, fleet utilisation, reliability trends, maintenance schedules and market availability. The goal is not simply to minimise inventory, but to optimise the total cost of engine availability while maintaining operational reliability. Anca Mihalache, Managing Director at AERO CARE has identified three key areas. “The main challenges are shop-visit turnaround times, MRO slot availability and parts availability. Currently, there are shortages and delays in delivery of almost everything, from expendables and consumables to LLPs. Airlines, lessors and even engine shops are all facing delays in sourcing parts for mature engines. As a result, shop visits are longer and slot availability is scarcer.” She then adds: “With engines being delayed in the shops, aircraft may remain on the ground awaiting return of their engines, and there are not enough spares available to cover the need for fast replacements. In my opinion, this is currently the biggest issue for operators. On top of this, there is the cost. In some cases, due to the lack of parts, the cost of a shop visit can exceed the catalogue list price (CLP), making it difficult for both operators and lessors to build a viable business case.”
For Mark Satran, Partner at Aero Engine Leasing, an affiliate of Aero Engine Solutions, the main challenge is uncertainty. “Airlines need enough spares to protect the operation against unexpected removals and longer-than-planned shop visits, but they do not want to tie up substantial capital in assets that may sit on the ground for extended periods. This is particularly relevant where we invest—in the one-generation-old narrowbody market, where CFM56-5B and -7B engines continue to support large A320ceo and 737NG fleets. Those fleets are remaining in service longer than originally anticipated, creating continued demand for reliable engine availability even as the industry transitions to newer-generation aircraft. For mature fleets, there is also a question of asset quality. Not all spare engines are equal. Remaining life, configuration, LLP status, maintenance history, records quality, and the timing and cost of the next shop visit can have a major impact on the true value of an engine,” he tells us. At Aero Norway, Jim Wylie, Director CFM56 T&M, believes that the biggest challenge is managing the cost and understanding the spare versus fleet size ratio. He goes onto suggest that: “As a fleet ages, the need for spare quantity can increase, and this will directly impact the budget. However, the challenge can be knowing when exactly the allocation needs to be baked in the annual budget. This is something that can be hard to see. The key piece of the puzzle is dependent on how well engineering and maintenance planning communicate. Having talented engineering staff is key to understanding how the fleet historically behaves. This knowledge, combined with a robust ‘end of life’ fleet plan, can help with the decision to own spares versus leasing spares.”
“There are currently many challenges facing airlines when managing their spare engine requirements,” says Walter Trujillo in the Engine Technical Department at APOC Aviation. “Engine repair shops are constrained by limited intake capacity, while shop visit TATs are also being extended by parts shortages and long lead times from specialist vendors. At the same time, OEM production rates for new spare engines are also being impacted by the same parts shortages, as well as the need to balance production with demand for replacement parts from engine shops,” he adds. Where Konrad Walter, Chairman, TMS Aero is concerned, operators for the most part all face challenges in managing spare engine requirements due to several factors. He goes on to detail some of these challenges: “Supply chain shortages of engine parts, as well as engine maintenance and repair services backlog, are the most critical problems we have today. We have seen for quite some time airlines operating older aircraft longer than expected due to “new gen” engine and aircraft issues whereas the engines are not staying on wing as long and other factors like aircraft deliveries being delayed as well. Therefore, many must revert to not only operating older aircraft but also leasing engines to hold them over.”
Oliver Smith, Origination & Trading Manager – Americas, EirTrade Aviation has also identified three key issues, though differing from those of Anca Mihalache. He states that: “Delays in new aircraft deliveries and the ongoing LEAP and GTF engine challenges have created a tight spare engine market. Fleet-wide engine maintenance campaigns have created simultaneous demand for spare engines across multiple airlines and strained availability. Airlines are subsequently extending the operational life of existing fleets, while longer MRO turnaround times and limited maintenance capacity are reducing the availability of serviceable spare engines. As a result, airlines face three key challenges: securing sufficient spare engine coverage, managing maintenance schedules around extended shop visit timelines, and controlling the increased costs associated with engine support.”
How do longer engine shop visit turnaround times affect airlines’ spare engine strategies?
Airlines are less inclined to keep as many owned spare engines as they used to, mainly because of the significant investment involved in assets that generate very little return. As a result, they have started planning their engine shop visits more carefully to avoid the need for spare engines or short-term leases, which can also come with operational risks. Anca Mihalache expands further on this: “However, delays in the shop, sometimes much longer than expected, can derail an operator’s plans. When this happens, operators often turn to short-term or green-time engine leasing,” she says. “Currently, the TAT for an engine shop visit is around 180–200 days, which is two to three months longer than it was a few years ago. Larger engine shops can mitigate this problem by offering a lease engine from the beginning of the shop visit. Another issue is that engine shops have now shifted part of their repair capability towards newer-generation engines, meaning there is increasing competition to secure slots at MROs with capacity and capability for legacy engine types,” she concludes.
Mark Satran feels that longer turnaround times effectively increase the number of spare engines an airline needs to support the same fleet. He goes on to tell us that: “As shop times have become materially longer, the airline has to cover the additional time somehow. The knock-on effect is the need for additional spares, leasing engines, or accepting greater operational risk. The issue is particularly relevant for CFM56-5B and -7B operators because A320ceo and 737NG aircraft are remaining in service longer. The continued utilisation of these aircraft, alongside the challenges of transitioning to newer-generation fleets, means airlines need to maintain access to sufficient engine capacity. Longer shop visits also make forecasting more difficult. An airline may plan around a particular engine returning by a certain date, only to find that material availability, work-scope changes, or MRO capacity push that date out. Having access to a leased spare can therefore be considerably more valuable than simply owning an additional engine, because it provides flexibility when the airline actually needs one.”
Turnaround time is a key factor for many where Jim Wylie is concerned. “Next to price and warranty, shop visit TAT is one of the most important contract conditions negotiated by an airline, lessor, or asset owner with an MRO. Planned engine removals for the purpose of booking maintenance are done far in advance, sometimes months or years. The primary reason it remains a focal point is because when an aircraft commercial or freighter is scheduled out of service, revenue from that aircraft cannot be achieved. The head of maintenance at the planning department must communicate the aircraft out of service schedules to senior leadership to understand quarterly and / or annual budget impacts. For engine off wing maintenance one of the alternate means of minimising revenue impact is to have spare engines that can be swapped on and off. In the case of a CFM56 this can happen as quickly as overnight. Spare engines can be carrier owned assets or leased from asset brokers. Owned versus leased is weighted by convenience or budget. When TAT unexpectedly slips, the engine that was installed now needs to stay on wing longer than planned. Therefore, if the asset is owned, the cost for that owned spare engine for the installed time frame is minimal. Compare this with the scenario whereby the engine installed is under a lease agreement. In this situation, the lease now needs to be extended which can be as much US$2K a day,” he warns.
“Extended shop visit TATs put airlines at a higher failure risk as operators may be pushed to run installed engines closer to maximum removal thresholds, increasing exposure to technical disruption. For example, even if an airline keeps one spare engine available for unexpected events, should this engine be used to compensate for excessive shop TAT’s, the risk of daily AOG situations rises significantly,” says Walter Trujillo, keen to highlight that there are certain strategies that may appear good in theory, but not in practice. Konrad Walter is also keen to point out how much rides on TATs. He advises that “Longer engine shop visits and reduced on-wing time of these engines make all these challenges and maintenance planning depend on spare engines and leasing thereof, which adds to operating cost. In short, shop visit turnaround times will always impact airlines spare engine strategies, due to maintenance repair, and engine MRO capacities are becoming harder to get slots and delayed by spare parts support…once again the need to lease or have more spares.” Oliver Smith makes a valid point that airlines are being forced to engage with outside resources when it comes engine management. “Typically, airlines manage their fleets in line with planned maintenance schedules. However, longer engine shop visit turnaround times, ongoing supply chain constraints, labour shortages, and limited availability of serviceable engines are forcing operators to plan maintenance events further in advance. Airlines are therefore increasingly engaging with OEMs, lessors, and asset managers to develop flexible spare engine strategies, including engine exchanges, short- and medium-term leasing solutions, and engine pooling arrangements,” he advises.
Extended shop turnaround times fundamentally change the way airlines must approach spare engine provisioning. Demetrios Bradshaw goes further with this: “When engines spend longer periods in maintenance due to material shortages, repair bottlenecks, LLP availability challenges, engineering dispositions or limited test cell capacity, spare engines remain in service much longer than originally planned. As multiple shop visits overlap, the available spare pool can quickly become stretched, increasing operational risk and reducing scheduling flexibility. Airlines should also focus on the total time an engine is unavailable rather than the quoted shop turnaround time alone. Removal, transportation, induction delays, scope growth, testing and return logistics all contribute to the actual period an engine is off wing. As a result, airlines increasingly need more sophisticated forecasting models, stronger maintenance planning disciplines and greater flexibility in accessing additional engine capacity when required.”
Are airlines increasingly moving away from owning spare engines towards leasing or other flexible access models?
Here we wanted to see if there was any identifiable trend shift in terms of engine ownership as a result of supply chain problems and lack of availability of certain specific and popular engines. Mark Satran certainly believes that there is a greater willingness to use leasing and other flexible access models, although he would not characterise it as airlines abandoning ownership altogether. He explains further: “There are good reasons to own certain spare engines, particularly where an airline has a large, mature fleet and can make efficient use of the asset over many years. Additionally, airlines have fixed capital budgets. Oftentimes, much of this capital is tied up in their fleet enhancement plans. Leasing engines provides access to additional capacity without competing for valuable capital asset dollars. There is also a core-competency argument. Airlines are in the business of flying passengers, and managing engine assets and overseeing complex shop visits—particularly on older engines that require more frequent maintenance—is not necessarily where they have the greatest expertise. Maintaining that capability internally can also result in higher costs.” He rounds off by saying that: “For an engine owner, the value proposition is therefore not simply the engine itself. It is the ability to provide a technically suitable, available engine when it is needed.”
Jim Wylie senses that as with any changes in operating methods for airlines, cost is the ultimate driver. “I believe owning or leasing spares is a much-needed scenario for airlines and, in some cases, having a mix of 40% owned and 60% leased is preferable. As the end of life for a given fleet plays out, having a stable full of spare engines can leave an airline with minimal return on investment due to the depreciation of the asset. Whereas, in comparison, a leased asset can be returned with no further financial burden. Where I see the market going is that airlines are moving to module swap as an alternative to longer TAT and lower cost shop visits. Airlines can simply partner with an MRO, such as Aero Norway, and draw up a business plan for module prebuild prior to shop visit and weigh out the financial model. The biproduct of module prebuilds for the purpose of quicker TAT is a shorter lease period. The long term of this type of planning could reduce quarterly or annual maintenance cost,” he suggests.
There doesn’t seem to be a one-size-first all solution for airlines based on what Walter Trujillo has to say. “There is no single industry view on owning spare engines compared to leasing or other flexible access models. The right approach depends heavily on an airline’s fleet size and cash flow capacity. It is also tied into the type of engine support contract in place, be that a flight-hour agreement (FHA) or managing shop visits on a time-and-materials (T&A) basis,” he comments, while Konrad Walter is more reserved in his opinion. He advises: “I wouldn’t go as far as saying airlines are moving away from owning spares…but are leaning towards leasing through the tough times and delays, as the OEMs cannot provide support for spare engines even during warranty repairs due to lack of spares themselves. We also need to take into consideration the costs associated with maintaining a larger inventory of spare engines.” Where Oliver Smith is concerned, he feels that “Engine ownership remains an important part of many airlines’ fleet strategies; however, modern aircraft engines are high-value, capital-intensive assets that can place significant demands on an airline’s balance sheet. Given the current market environment, many operators are increasingly supplementing owned spare engines with leased assets, engine pooling arrangements, and other flexible solutions. Leasing spare engines can reduce upfront capital expenditure and provide greater operational flexibility, particularly during maintenance events or periods of unexpected engine removals. While airlines remain responsible for maintenance costs through lease payments and maintenance reserve contributions, these arrangements can help smooth cash flows and provide access to serviceable engine capacity without the need for outright ownership. As a result, many airlines are adopting a hybrid approach, maintaining a core inventory of owned spare engines while utilising leasing and pooling solutions to meet short- and medium-term operational requirements.”
It would be fair to say that the industry is certainly moving towards more flexible access solutions, although it would be inaccurate to describe this as a widespread shift away from ownership. Increasingly, the most effective strategy is a hybrid model. Beyond this, Demetrios Bradshaw believes that “For operators with larger and more stable fleets, ownership of a core spare engine portfolio continues to offer significant advantages, including guaranteed availability, greater configuration control and protection from fluctuations in the leasing market. However, acquiring enough engines to cover every potential peak requirement can be highly capital intensive and may lead to underutilised assets during normal operations. Leasing, pooling, exchange programmes and other structured access solutions enable airlines to add flexibility around that core owned fleet. These solutions are particularly valuable during periods of heavy maintenance activity, unexpected removals, OEM campaigns or prolonged shop turnaround times. That said, airlines should evaluate far more than the headline lease rate. Considerations such as lease duration, utilisation charges, LLP exposure, maintenance obligations, return conditions, configuration requirements and logistics costs can materially influence the overall economics of a transaction. Ultimately, the key strategic question is not whether to own or lease, but which portion of demand is predictable enough to justify ownership, and which should remain flexible.” Meanwhile, Anca Mihalache is unequivocal in her opinion. “Yes, I think this is particularly the case for legacy engines. For newer-generation engines, however, I think airlines will still prefer to have spare engines ‘ready to go’, as there are not many of these newer engine types available to lease in the current market. As fleets evolve and mature engines are increasingly retired, there will still be a need for spare engines that are immediately available, rather than having to wait for a lease agreement to be negotiated and signed. This becomes particularly important in the case of unexpected events such as foreign object damage (FOD) incidents, where immediate engine availability can be more important than whether leasing would theoretically be the more economical option.” She then concludes that: “For a large, stable fleet that an airline expects to operate for many years, owning a pool of spare engines can still make very good economic and operational sense. It gives the airline control over availability and avoids complete exposure to the lease market.”
What factors should airlines consider when developing a long-term spare engine strategy?
Jim Wylie at Aero Norway highlights three factors to consider for an effective spare engine strategy. He details them as follows. “Utilisation cycles versus hours e.g. LLP cycle burn down: Airlines must have long-term planning to calculate each engine’s approximate date for LLP cycles consumed. With this information, they then must stagger each removal with consideration to shop TAT. Engine performance deterioration: Utilising the onboard diagnostic information, aircraft engineers need to assist the maintenance planning teams with calculated performance deterioration approximate dates. These dates can then be used to develop the engine removal stagger plan. Unscheduled engine removals: Unscheduled engine removal historical trend(s) can be gleaned from the airline’s past experiences, or via data supplied by engine OEMs. However, it is worth noting that the latter is based on global fleet historical data.” He further feels that: “These three factors all drive the need for spare engine management, but the flexibility and commitment from a trusted MRO like Aero Norway will allow for a successful fleet plan with ample spare engine capacity,” before he suggests we consider the following scenario: “Ten engines on wing; max LLP 20K cycles; performance deterioration can happen between 15k cycles – 20K Cycles; typical UER rate is three/year, shop visit TAT 120 days. How many spare engines does the airline need?”
For Walter Trujillo at APOC Aviation, he believes “A key factor airlines should consider when setting their long-term spare engine strategy is dispatch reliability and the ratio of spare engines to fleet size. But it also needs to reflect the airline’s cash flow capacity, expected engine shop visit costs and type of contract – and so level of risk transfer – in place to manage shop visits. APOC can support operators with ‘green-time’ engine lease solutions, particularly when airlines are phasing out older engine types or transitioning from previous-generation technology to newer variants.” On the other hand, Konrad Walter at TMS Aero suggests that there could be several factors. He advises further: “While leasing allows airlines to avoid tying up capital for spare engines one would have to consider both having your own spares based on their operation and having lease engines available for short term purposes when engines are going through shop visits. Flexibility is key here while prioritising availability and response to fluctuating operational needs and what could be the burden of owning versus leasing.”
As far as Oliver Smith at EirTrade Aviation is concerned: “Airlines should align their long-term spare engine strategy with their fleet plans, maintenance forecasts, and anticipated engine shop visit requirements. Key considerations include fleet growth, retirement schedules, engine reliability, MRO capacity, turnaround times, and spare engine availability. Given the current supply chain and maintenance constraints, operators must also evaluate market conditions and determine the most effective means of securing spare engine coverage, whether through ownership, leasing, pooling arrangements, or green-time solutions.” Meanwhile, Demetrios Bradshaw at Aeras Aviation is very much of the opinion that a successful long term spare engine strategy should be built around the airline’s fleet plan and maintenance requirements rather than a fixed target number of spare engines. He goes on to advise that: “Operators should model fleet growth, utilisation levels, engine removal rates, scheduled shop visits, LLP forecasts, reliability trends, expected time on wing and realistic maintenance turnaround times. These assumptions should then be tested against potential disruptions such as unscheduled removals, durability issues, regulatory requirements, OEM modification programmes, aircraft delivery delays and material shortages. Technical interchangeability is another critical consideration. Engine model alone does not determine fleet flexibility. Build standard, thrust rating, modification status, LLP life, QEC requirements and installation configuration can all influence whether an engine can be efficiently deployed across the fleet. From a commercial standpoint, airlines should combine ownership, leasing, pooling and exchange capabilities with secured maintenance capacity and a disciplined material strategy, including the selective use of certified used serviceable material where appropriate.” He rounds off by suggesting that: “… operators should evaluate the entire economic lifecycle of each asset, including acquisition cost, maintenance exposure, green time, LLP value, leasing potential and residual value. The most effective spare engine strategies bring together engineering, maintenance planning, operations and finance within a single decision-making framework. A spare engine should not be viewed merely as inventory on a balance sheet. It is a strategic asset that protects aircraft availability, supports schedule integrity and safeguards revenue generation.”
At AERO CARE, Anca Mihalache believes that predictability is the most important factor. However, she adopts a slightly cautious tone as she explains: “Of course, with newer-generation engines, it is not easy to predict requirements as there is not yet a great deal of historical data. However, as more of these engines enter service, better predictability and good planning will be lifesaving. Then, there is the choice of engine shop to consider. If an operator chooses an engine shop that can also provide short-term leasing options, it may be able to operate with fewer spare engines.” To conclude the above question, Mark Satran at Aero Engine Leasing feels that the starting point should be operational requirements rather than simply a target number of spare engines. He believes: “Airlines should consider fleet size and utilisation, expected removal rates, historical reliability, MRO turnaround times, and the level of operational disruption they are willing to tolerate. They should then compare the economics of ownership versus access. An owned spare requires capital and carries costs associated with financing, storage, maintenance, and future shop visits, as well as residual-value risk. Leasing provides greater flexibility and can allow an airline to match engine availability more closely to its actual requirements. The expected life of the fleet is also increasingly important. Airlines need to consider how long they will operate their CFM56-powered A320ceo and 737NG aircraft as fleet transitions continue. A strong strategy is ultimately about having reliable access to the right engines when they are needed.”
How can operators balance the cost of holding spare engines against the operational risks of insufficient spare coverage?
There is no avoiding the consequences of delays in the production of new aircraft seeing fleets operating beyond their planned retirement, combined with a shortage of available P&W GTF and CFM LEAP engines, not just for new aircraft, but as standalone spares and replacements for carriers and MROs. So what strategies are proving most effective when dealing with such a challenge?
“Balancing the cost of spare engine ownership against operational risk requires operators to plan for both scheduled maintenance removals and unscheduled AOG events. While spare engines represent a significant investment, insufficient coverage can quickly lead to aircraft downtime, schedule disruptions, lost revenue, and reduced fleet reliability,” says Virgil D. Pizer, Chief Executive Officer, Pem-Air Turbine Engine Services. He goes on to say that: “From an MRO perspective, the first step is understanding an operator’s maintenance profile. Scheduled removals for shop visits, overhauls, and life-limited part replacements can typically be forecast well in advance. However, unexpected engine issues can occur at any time, making it important to have a strategy that addresses both planned and unplanned events. This challenge is often more significant for smaller and mid-sized operators. With limited fleet redundancy, the removal of a single engine can have a disproportionate impact on operations. In these cases, owning multiple spare engines may not always be economically practical. This is where strong partnerships with both an MRO provider and a lessor can help relieve some of the pressure. An experienced MRO partner can provide greater visibility into engine health, maintenance forecasts, and upcoming shop visit requirements, allowing operators to plan more effectively and reduce surprises. At the same time, lessors can offer access to spare engine assets or flexible leasing solutions that provide coverage without the capital commitment of outright ownership. By working together, operators, MROs, and lessors can develop a more flexible spare engine strategy that aligns maintenance planning with available engine resources. This collaborative approach helps ensure coverage for both scheduled maintenance and unexpected events while reducing the financial burden of maintaining a large spare engine inventory. Ultimately, the goal is not to eliminate risk but to manage it effectively. For many smaller operators, the right combination of proactive maintenance planning, MRO support, and flexible access to leased or pooled spare engines can provide the operational resilience they need without tying up excessive capital.”
Robbie Deegan, Senior Manager Contracts and Asset Management, Setna iO sees this very much as a constant battle for operators. He further comments that: “Of course, every fleet is different, as are strategies across regions. Taking the USA, a recent Reuters analysis of U.S. Transportation Department data found that across six large U.S. airline operations, reported spending on engine labour, aircraft-engine repairs and engine materials rose about 68% between 2019 and 2025, while hours flown increased about 10%. Therefore, operators should compare the annual cost of owning or leasing an additional spare engine with the expected cost of insufficient coverage, including AOG losses, aircraft substitution, passenger disruption and emergency short term engine-leasing costs. The optimal strategy is not to hold the maximum possible number of spares, but to maintain enough coverage to keep the probability and financial impact of an engine-related grounding within an acceptable level. Operators could also consider having pre-agreed lease contracts in place with some of the dedicated spare engine lessors and keep in regular contact regarding spare engine availability particularly when supply is tight and demand high for spare engines. For organisations such as us at Setna, providing in stock, ready to go USM ultimately keeps engines flying longer whilst reducing downtime for operators.” Matt Power, Sr. Director Engine Leasing, StandardAero is direct and succinct in his thoughts on the matter. “Options available to operators seeking to minimise the capital outlay associated with spare engines include the use of lease assets (which can also include sale and leaseback deals associated with existing spare engine inventory); the utilisation of engine lease pools (where offered); and partnerships with asset management specialists who may be able to offer cost-effective solutions such as guaranteed access to green-time engines with specific cycles remaining (CR) to meet the airline’s particular requirements,” he tells us. Cliff Topham, SVP & Head of Engines, Werner Aero LLC is equally concise, while presenting very viable options. He feels that: “Balancing is primarily dependent on the risk acceptable to the operator – however the market has changed over recent years. There are alternative ways to balance that risk as opposed to basically having the spare engine assets owned by the operator. Some of these are long term leasing (financing), operational leasing and pooling, in times of oversupply of green time engines, some operators can feel relatively comfortable having zero committed spare engine coverage and rely on the short-term lease availability.”
Are the challenges of spare engine management different for new-generation engines compared with mature engine programmes?
There clearly are differences, though depending on your relationship with engines, the challenges may well vary considerably. We were keen to discover what these differences might be. Robbie Deegan has more to say on the matter: “Yes, the key difference comes down to uncertainty around new-generation engines. Less long-term operating experience is always going to result in greater unpredictability when it comes to planning engine removals. For example, IATA reported that 648 Pratt & Whitney GTF-powered aircraft were grounded at the peak in March 2025, highlighting the operational impact of engine availability problems. However, as these problems are resolved by the OEM’s, and the engines begin flying over a longer period of time, this will result in a greater ability to plan from an operational perspective in the future.” For Matt Power, one of the most notable changes associated with new-generation spare engine management in recent years has been obtaining cost-effective access to spare engines, at a time when these powerplants have been in high demand (and limited supply), resulting in extremely high valuations. He goes on to say that: “Aside from this, another obvious challenge associated with new-gen spare engines is the issue of configuration management, at a time in the powerplant’s lifecycle when OEMs may be releasing upgrades to address early service issues. Finally, new-gen engines early in their service life may also experience shorter time-on-wing (TOW) compared to older engines, necessitating more frequent MRO shop visits (which may be longer than anticipated due to MRO induction times and/or parts shortages).”
“Unfortunately, yes in general, the challenges of “new generation” engines have been made more difficult in main due to the lower on-wing life not only to that originally expected lives, but also in comparison to the older generation engines the latest technology engines were due to replace,” comments Cliff Topham. “The outcome of this is that the ratio of spare engine support needed is in general greater than that accepted by the organisation used to operating the older generation engines. The OEMs are doing their best to support these additional requirements but it’s fair to say there is still some work to go in times of durability and life on wing,” he adds. For Virgil D. Pizer the challenges can be quite different, though he feels the underlying objective remains the same: ensuring engines are available when operators need them while minimising operational disruption. He goes on to explain that: “For newer-generation engine programmes, operators are often working within an aftermarket ecosystem that is still evolving. Growing fleet populations, increasing maintenance demand, limited spare engine availability, and developing repair networks can all place pressure on spare engine planning. In these environments, securing access to spare assets often requires significant advance planning and close coordination among operators, lessors, and maintenance providers. Mature engine programmes present a different set of challenges. While maintenance practices, reliability trends, and shop visit requirements are generally well understood, operators must manage aging assets, parts availability concerns, and long-term lifecycle decisions. The focus often shifts from building maintenance capability to maximising asset value and extending the useful life of engines in a cost-effective manner. From Pem-Air’s perspective, one of the key advantages of mature engine programmes is the strength of the support ecosystem that has developed around them. Years of operational and maintenance data, established repair capabilities, available serviceable material, and close collaboration between operators, MROs, and lessors can provide greater flexibility when managing both scheduled maintenance events and unexpected removals. This is particularly important for smaller and mid-sized operators. Rather than relying solely on owned spare engines, many benefit from a collaborative model involving the operator, the MRO, and a lessor. The operator gains visibility into upcoming maintenance requirements, the MRO helps forecast shop visits and maintenance needs, and the lessor can provide access to spare assets when additional coverage is required. Together, this helps reduce uncertainty and improve operational resilience without requiring significant capital investment in spare inventory. Ultimately, regardless of engine type, successful spare engine management depends on proactive planning and strong partnerships. The more effectively operators can connect maintenance planning with asset availability, the better positioned they are to navigate both scheduled and unexpected maintenance events.”
What is the most common mistake airlines make when managing spare engine availability?
Matt Power is quite clear on his choice. “One of the most common mistakes that we see is operators underestimating (or shortcutting) their spare engine ratio. This is an issue which has been particularly exposed with those new-gen engines which have been seeing lower than expected TOW due to early service issues. In a similar vein we have also seen some operators over-estimate their ability to secure lease engines on the open market, which has – as a result – impacted their spare engine strategy,” he states. On the other hand, Cliff Topham senses there is more than one mistake that you will find near the top of the list. He lists these as: “Not keeping it in the most favoured condition for rapid engine change usually referred to as full QEC, or EBU’d engines. In certain airplane platforms there are different configurations for Left-Handed engines and Right-Handed engines, which means that the engines should be configured into Max Neutral QEC configuration, i.e., a condition that allows the shortest build and installation time for any aircraft engine position. Not provisioning the correct thrust specification of engine to cover the fleet. In general, if a mixed fleet of aircraft are operated it is important that the highest thrust requirements are provisioned. Not keeping engine stands in usable condition and not having the paperwork ready to install the engine”
Like Cliff Topham, Virgil D. Pizer feels there is more than one mistake to highlight. He begins: “One of the most common mistakes is treating spare engine planning as a reactive exercise rather than a long-term strategic process. Many operators understandably focus on unexpected engine removals and AOG events, but the greater challenge is often failing to adequately plan for scheduled maintenance requirements well in advance, especially in today’s tight market environment. From an MRO perspective, scheduled shop visits are generally predictable. Engine utilisation, life-limited part cycles, and maintenance requirements provide operators with visibility into future engine removals. However, when maintenance planning, spare engine strategy, and shop capacity planning are not aligned, operators can find themselves competing for limited spare assets or facing longer-than-expected downtime.” He then goes on to add that: “Another common challenge is underestimating the cumulative impact of market conditions. Engine availability is influenced not only by an operator’s own fleet requirements, but also by industry-wide factors such as MRO capacity, parts availability, and demand for leased or pooled spare engines. Waiting until a removal is imminent can significantly reduce the number of available options. For smaller and mid-sized operators, this risk is often amplified because there is less fleet redundancy to absorb an unexpected event. A single engine removal, whether planned or unplanned, can have a meaningful impact on operations if adequate coverage has not been arranged. Pem-Air, as an MRO partner, sees the most successful operators taking a proactive approach. They engage early in maintenance planning discussions, maintain visibility into engine health and upcoming shop visits, and work closely with MROs, lessors, and asset providers to ensure spare engine requirements are identified well in advance. Ultimately, spare engine management is most effective when it is integrated into the broader maintenance strategy. The goal is not simply to respond to engine removals, but to anticipate them and ensure the right resources are available before operational disruptions occur.”
In your view, what does an ideal spare engine solution look like: ownership, leasing, pooling, or a combination of all three?
Where Robbie Deegan at Setna iO is concerned, this varies depending on fleet size, region and cost of capital, as examples. He then explains that: “If we take large operators, a mixed strategy is likely the best approach for them. The reason for that is that a single strategy can be expensive or have limitations. For example, ownership alone is expensive, and leasing can expose airlines to high prices and limited availability when demand is highest. At Setna, we are leasing and trading engines but also providing them with the required material reduce repair cost and repair time for older generation engines and aircraft, and we envisage this being the same with the new generation of assets in the long term.” Over at Standard Aero, Matt Power at Standard Aero has useful insights as he tells us: “The optimal spare engine solution will depend on an airline’s specific preferences (including capital outlay and risk tolerance), with some carriers preferring to assure their access to spare engines via a large owned pool, and others preferring to minimise their sunk capital through the use of leased or pooled assets. The fact that operators are able to choose from these options (and others, including the use of green-time assets and third-party fleet management) does give airlines more flexibility than in years past, and should reduce the risk of unexpected AOG events.”
“In general, this very much depends on the size and variety (model thrust standard operated) of the fleet,” says Cliff Topham at Werner Aero LLC. He then goes on to tell us that: “The larger the size of the fleet, and the more common fleet operated, the more this is skewed towards ownership of spare engine assets to support the fleet. In today’s world there is always a case for reviewing these requirements both from a short-term and a long-term point of view and most likely a mixture of the three types outlined above can provide a better balance of cost versus lack of availability costs. These also change with age of fleet and assets e.g., as aircraft are phased out many airlines are these days looking at keeping engines installed in the to be phased out aircraft to support the remainder of the fleet particularly if they have low book value and good “green time” i.e., remaining useful life.”
Virgil D. Pizer at Pem-Air brings this article nicely to a close with a very comprehensive outlook for an ideal spare engine solution. “In our experience, there is rarely a one-size-fits-all solution. The ideal spare engine strategy is typically a combination of ownership, leasing, and pooling arrangements, tailored to an operator’s fleet size, utilisation, financial objectives, and operational risk profile. Ownership provides the highest level of control and guaranteed access to an asset when it is needed. For operators with larger fleets or consistently high utilisation, owning spare engines can make strategic sense, particularly when there is a predictable demand for coverage during scheduled maintenance events. Leasing offers greater flexibility and can be an attractive option for operators looking to preserve capital while maintaining access to spare assets. It is especially useful when covering planned shop visits, temporary capacity shortfalls, fleet growth, or unexpected engine removals without the long-term commitment of ownership. Pooling arrangements can also provide valuable flexibility, particularly for smaller and mid-sized operators that may not have the scale to justify significant spare engine ownership. Shared access to assets can help improve resilience while reducing capital requirements. From an MRO perspective, however, the most effective solution is often not defined by a single asset strategy but by the strength of the partnership supporting it. When operators, MRO providers, and lessors work together, they can create a more proactive and flexible spare engine ecosystem. The operator gains greater visibility into upcoming maintenance requirements, the MRO helps forecast shop visits and maintenance needs, and the lessor can provide access to spare assets when coverage is required. This collaborative model helps reduce uncertainty around both scheduled maintenance events and unexpected removals. Rather than relying solely on owned inventory, operators can leverage a broader network of maintenance expertise, asset availability, and planning support to maintain operational continuity. Ultimately, the best spare engine solution is one that aligns maintenance planning with access to available assets. For many operators, particularly smaller and mid-sized fleets, a combination of owned, leased, and pooled resources supported by strong MRO and lessor partnerships provides the greatest balance of flexibility, cost efficiency, and operational resilience,” he concludes.